Understanding Your Solar Financing Options: Loan vs. Lease
Investing in a residential solar system can be a significant decision for homeowners. With various financing options available, it’s essential to understand the differences between solar loans and leases. This article will explore these two primary financing methods, helping you determine which might be the right fit for your situation.
The Basics: What Is a Solar Loan vs. a Solar Lease?
Before diving into the pros and cons of each option, it’s important to clarify what a solar loan and a solar lease entail.
- Solar Loan: This financing option allows you to borrow money to purchase a solar energy system. As the owner of the system, you are responsible for the installation, maintenance, and any applicable property taxes. You repay the loan over time, typically through monthly payments.
- Solar Lease: A solar lease is a rental agreement where you pay a fixed monthly amount to use the solar system installed on your property. The leasing company owns the system, handles maintenance, and typically guarantees a certain level of performance.
Key Considerations: Ownership and Responsibility
Ownership Benefits
With a solar loan, you own the system outright once you pay off the loan. This ownership can lead to several benefits:
- Tax Benefits: As the owner, you may be eligible for federal tax credits and other incentives.
- Increased Home Value: A purchased solar system can potentially increase your home’s resale value.
- Full Energy Savings: You keep all the energy savings generated by the system, potentially reducing or eliminating your electricity bills.
Leasing Considerations
On the other hand, a solar lease might be appealing for those who prefer a more hands-off approach:
- Lower Upfront Costs: Leasing typically requires little to no upfront payment, making it more accessible for some homeowners.
- No Maintenance Hassles: The leasing company handles maintenance and repairs, relieving you of these responsibilities.
- Predictable Payments: Fixed monthly payments can help with budgeting and financial planning.
Financial Tradeoffs: Costs and Savings
When comparing loans and leases, consider how each option impacts your finances over time. Here are some factors to weigh:
Monthly Payments
With a solar loan, your monthly payments may be higher than a lease, particularly in the initial years. However, as you pay down the loan, you could eventually eliminate these payments altogether, leading to significant long-term savings. In contrast, a lease often involves consistent monthly payments that can last for 20 years or more.
Overall Costs
It’s crucial to assess the total cost of ownership versus leasing. While leasing may seem cheaper upfront, owning the system can be more cost-effective over time due to tax incentives and energy savings. Be sure to factor in:
- Loan interest rates
- Lease escalation clauses that might increase payments over time
- Potential maintenance costs if you choose to own
Long-Term Considerations: Length of Commitment and Flexibility
Another important factor in your decision is how long you plan to stay in your home and your financial flexibility.
Homeownership Plans
If you plan to remain in your home for many years, a solar loan may provide better long-term benefits through ownership. However, if you anticipate moving within a few years, a lease could be advantageous, as leases often allow for easy transfer to new homeowners.
Flexibility and Upgrades
Consider how financing affects your ability to adapt to future changes:
- Upgrading Systems: If technology improves or your energy needs change, owning your system might allow for easier upgrades compared to a lease.
- Financial Flexibility: Loans might offer the ability to refinance or pay off early, while leases typically bind you to a long-term contract.
Example Scenarios: When to Choose Each Option
Understanding specific scenarios can help illustrate when a loan might be more suitable versus a lease:
Scenario 1: The Long-Term Homeowner
If you own a home, plan to stay for at least a decade, and have the financial capacity to manage higher upfront costs, a solar loan could be your best bet. You’ll benefit from ownership and the associated tax incentives, ultimately leading to greater savings over time.
Scenario 2: The Short-Term Mover
If you’re unsure about your long-term plans or expect to move within the next few years, a solar lease may make more sense. It allows you to enjoy the benefits of solar energy without the commitment of ownership, and you can transfer the lease to the new homeowner.
How to Make Your Decision
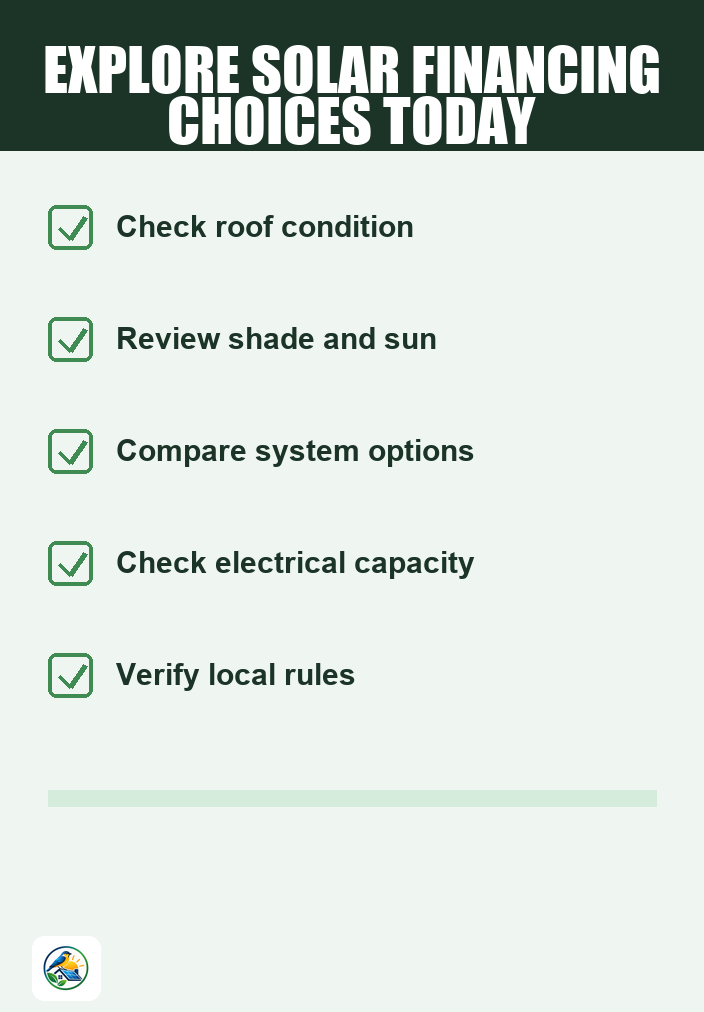
To determine the best financing option for your situation, follow these steps:
- Evaluate your financial situation, including your credit score and available cash for upfront costs.
- Consider your long-term housing plans and how they align with each financing option.
- Request detailed quotes from multiple qualified solar installers, comparing itemized costs, terms, and conditions for both loans and leases.
- Consult with financial advisors, if necessary, to understand the implications of each option on your personal finances.
Next Steps: Get Quotes and Verify Local Information
As you navigate your solar financing options, securing itemized quotes from qualified installers is crucial. This will help you understand the specific costs and financing options available for your home. Remember to verify any local incentives, utility policies, and financing rates before making your final decision. With careful consideration and thorough research, you’ll be well-equipped to choose the right path for your solar investment.